For Texas owners
LLC Partnership Taxes, for Texas owners
You and the other owner can sign one federal partnership return in March and still have a Texas packet that neither K-1 names.
Dallas, and the screen after that
Steven Palmieri keeps this practice in Dallas, and the hour with both of you is a video call when you can both join. The agreement fills the shared screen. Last year's K-1 stays in that same view. A caller in another state uses the screen. A caller in a Texas town past Dallas and Fort Worth uses it too.
Houston, Austin, the Gulf, the Hill Country, and the Panhandle are towns a caller may live in, and none of them is a second room this practice keeps. Reading from past the cities we can drive, you still hear the hello we would give a neighbor, because we are all Texans, and the partnership return you both sign does not shift just because the scanner sits on the far side of the state.
Every other page at this address stays with the federal stack, the agreement, the cash, and the K-1. This page is the one that names the Texas packet. Bring both stacks to the hour. People describe relief at the moment each stack has its own name, and the fear that a single March signature closed every file can finally sit down.
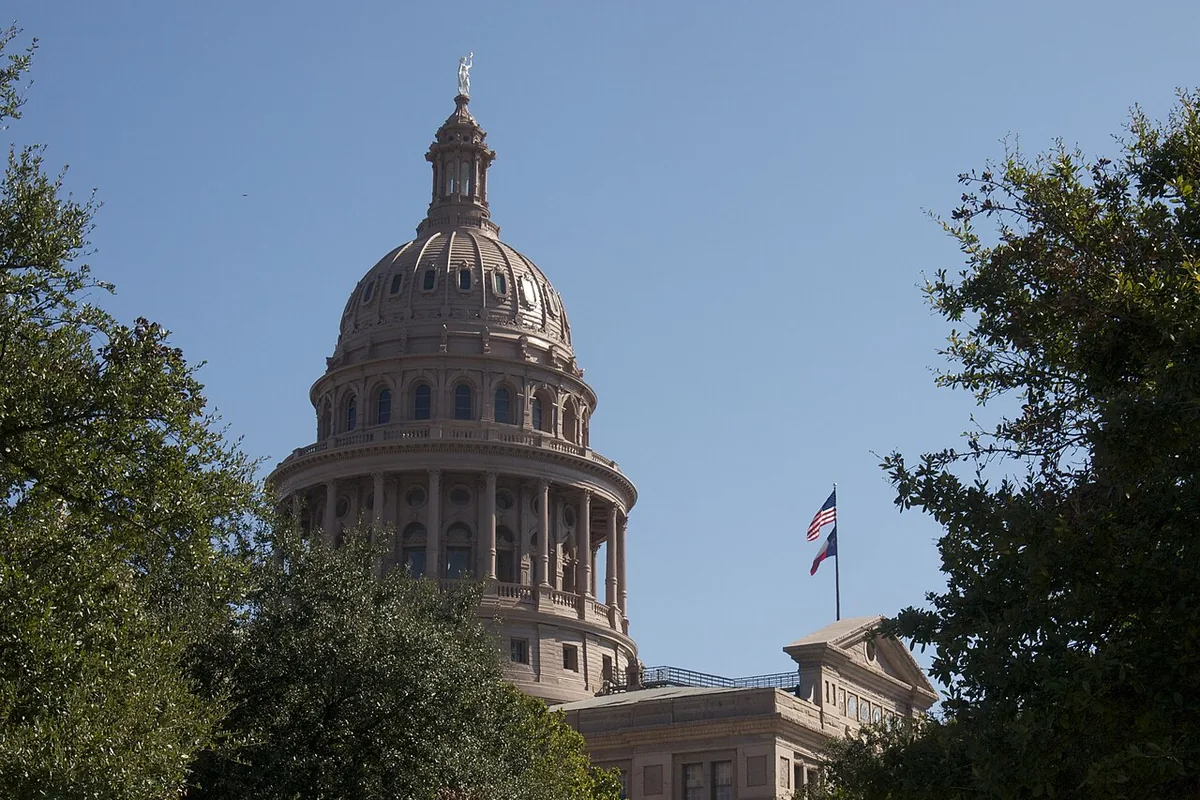
The photograph at the top of this page is the Texas State Capitol in Austin, dome and flags among the trees, by Capvideo, used under CC BY-SA 4.0.
The company and the federal life
Until some later election is accepted, two or more owners usually mean a partnership on the federal return. That federal life is Form 1065 plus a K-1 for each of you. Texas is asking a different question, and we set Publication 98-806 beside the agreement because that booklet walks through the privilege tax the Comptroller lays on a taxable entity organized in Texas or carrying on business there.
Limited liability companies stand on the booklet's list, and so does a series company, and so does a company with only one member. You will also find corporations, banks, S corporations, partnerships, trusts, professional associations, and joint ventures written there, which is why the federal label does not by itself answer the state question for two owners.
Two natural persons who never formed a company, and who hold only a general partnership, are usually left off that list. Put limited liability around the same partnership and the booklet pulls the firm back on. If one of you has been filing with no company at all, as a sole proprietor, that person is usually off as well, unless the work in fact lives inside a single member limited liability company.
Here is the split the two of you can miss. Forming a limited liability company can leave the federal return a partnership and still leave the Comptroller expecting a report. Stay two natural persons in a general partnership, with no company ever formed, and there may be no franchise report to sign. Initials printed on a certificate do not pick that label. When the live question is whether this company is doing business in Texas, the booklet sends the reader to Rule 3.586 for examples, and we lay those examples against this company's own facts.
Chapter 171 of the Tax Code already names some entities exempt, and those names stay off the filing pile for a year the exemption holds. A year gets called passive only while that year's facts still match the label, and only then does the entity stay off. The federal return and this state report are allowed to tell different stories about the same two owners. A quiet letter that the federal return is in order can still leave the state file sitting open.
What the margin can count
With the long form as the sheet in front of both of you, Publication 98-806 gives four computations, and a combined group, if you have one, has to share a single choice. Choice one counts seven tenths of total revenue and sets the remaining three tenths aside. One reduces total revenue by cost of goods sold. One reduces total revenue by compensation. One reduces total revenue by one million dollars, and that subtraction has been open since January 2014.
Both of you begin with the federal revenue figure, and Tax Code section 171.1011 is the list of amounts that then come off before this report calls the remainder total revenue. Goods you may subtract are, in the main, property someone can touch and real property, provided the company sold that property in the ordinary course of the year the two of you are signing. Two owners whose work is services often find nothing they can subtract in that spot, aside from industry exceptions written into section 171.1012. We will not invent a goods figure so a service year has a number in the blank.
W-2 wages can sit inside compensation on this report, and so can cash the company paid to officers, directors, owners, partners, and employees. Net distributive income that reached a natural person can sit there too, stopped at the per person cap for the report year in front of you, and so can benefits the report allows, among them workers compensation, health coverage, and retirement contributions. Money that left on a 1099 does not enter that compensation pile. The employer half of payroll taxes does not enter it either. Between the two of you, that pile is how the talk walks back to the K-1. Up to the cap, a distributive share can feed the subtraction. A contractor's 1099 has no path into it. Name a guaranteed payment for what it actually is before either owner lets it fall into the wrong pile.
Texas gross receipts are what spread a chosen margin across the state. No amount printed here was lifted from a return anyone filed. A labeled example, if we draw one, is invented.
Two report years, side by side
Read 2026 as its own report year, and then read 2027 as its own. In both of those years, annualized total revenue of 2,650,000 dollars is where the franchise tax itself falls away while the tax report stays unfiled. The franchise tax can drop off and the Comptroller can still be waiting on the information pages. The public half of that information filing, the half a stranger can read, is Form 05-102. Ownership detail that stays confidential goes on Form 05-167. A limited partnership organized in Texas, or holding nexus in Texas, files Form 05-102, in the same group as corporations, limited liability companies, professional associations, and financial institutions. Anyone taxable who is outside that Form 05-102 cluster, and who was organized in Texas or holds nexus in Texas, uses Form 05-167.
Even when revenue sits at that line or under it, the information report is still due, unless the company is already on the Comptroller's skip list. Each named member still sends a report when the group files together, if that member was organized in Texas or still has nexus there. Names that skip both forms include exempt entities, passive entities, entities with neither Texas organization nor Texas nexus, and qualifying new veteran owned businesses through their first five years.
2024 and 2025 were a different pair of years. For the 2024 report and again for the 2025 report, franchise tax dropped away at annualized total revenue of 2,470,000 dollars, and the cap on compensation you could subtract was 450,000 dollars. Park both of those ceilings on the 2024 report and on the 2025 report, and nowhere later. Signing 2026 with either of those older ceilings would pin this year to a number that belonged to a year already closed. The older paper whose only job was to announce that no tax was due was retired beginning with report year 2024. That older paper is not the filing in your hand.
For report years 2026 and 2027, margin from retail work and margin from wholesale work are both figured at 0.375 percent. Margin from work that is not retail and not wholesale is figured at 0.75 percent in each of those years. In 2026 the compensation deduction caps at 480,000 dollars, and in 2027 that same cap of 480,000 dollars applies again. If annualized total revenue is 20 million dollars or under, the 2026 report and the 2027 report may use the EZ computation, at a rate of 0.331 percent, and using EZ leaves the margin deductions unused on that report. Cross above 20 million dollars of annualized total revenue, or keep a margin deduction, and you are on the long computation.
May 15, and the days after it
The franchise report is built to be signed on May 15. If that calendar day is a Saturday, a Sunday, or a holiday the Comptroller observes, the signature slides to the following business day. A report that shows up after the due day draws a penalty of 50 dollars, and that penalty is counted before anyone turns to the tax itself. During the thirty days right after the due day, tax that comes in carries an extra 5 percent of itself. Tax still open once those 30 days have passed grows by 10 percent of the tax. Interest begins on day 61. The interest percent for the year on the signature line is printed on the Comptroller interest page, so we point there and we do not reprint it.
The extra days exist only after a payment has arrived by the original due day, or after the Comptroller's form has arrived that same day. One route sends 100 percent of the prior year's tax. The other route sends 90 percent of the tax this report will actually owe. There is no prior-year route for a company whose first annual report is also the first year the tax applies to it. November 15 remains open to a company that pays some other way than electronic funds transfer, by Webfile or by Form 05-164.
Electronic funds transfer becomes mandatory after the company paid at least 10,000 dollars during the state fiscal year that just closed. Extra time for that payer can first run out to August 15, and can next run out to November 15. If those earlier payments have already reached 500,000 dollars, the request for extra time is a TEXNET payment under code 13080 that gets there while it still counts as on time, and Form 05-164 is not filed alongside it. What hour still counts a large TEXNET payment as on time is written on the year's own instruction. We read that instruction next to the signature. The hour is not one we keep in memory.
The final report comes due once 60 days have passed from the loss of sufficient nexus. Where the extension payment rules are already met, extra time on that final report runs 45 days past the final due day. Ending the company, or ending the Texas tie, is a decision the two of you make. The papers in that ending are the final report and a certificate of account status issued by the Secretary of State. Before we say which paper comes first, we read the close instructions that are current.
If the information report never gets filed, forfeiture is what sections 171.251 and 171.2515, then 171.252 and 171.255, of the Tax Code describe. The loss can include the right to sue or to defend in a Texas court, and it can include personal liability of officers, directors, partners, members, or owners for certain debts. Sections 171.259 and 171.260 hold those forfeiture provisions off financial institutions. Once this year's report is filed, a new officer's name does not ride along until next year's report, unless you send an amendment because a fact was wrong or because the need cannot wait. A new registered agent is sent to the Secretary of State, on that office's own form, and the change is not written onto Form 05-102 or onto Form 05-167.
On January 1, 2026, the filing rules for the research credit changed. The franchise home page is where that change is pointed out. If this year might use the credit, we follow that page, rather than a summary remembered from an older season.
Sales tax, if the partnership sells
Sales tax is not something a K-1 collects. Sell mostly goods, or sell a service the state has listed as taxable, and the Comptroller expects a return that stands apart from the partnership return. The state's own slice of a taxable sale is 6.25 percent, and only after that slice does a city, a county, or a transit district get to add local tax, up to 2 percent. Stacked on a single sale, the buyer is not charged past 8.25 percent. Which place the sale belongs to is what sets the local piece, and that piece is looked up on the Comptroller rate locator the day the sale happens. City rates live on the Comptroller rate locator. Both of you look the city's number up on the day the sale happens, because a number frozen in this paragraph would be the wrong number the week that city changes it.
The letter that follows an approved permit is the letter that tells the two of you whether the rhythm is monthly or quarterly. When the permit letter says monthly, the month that just closed is reported on the 20th of the following month. April's report, to take one month, is due May 20. Four times a year, a quarterly seller reports: once when April arrives, once in July, once in October, and once in January. On a yearly rhythm the prior year is reported on January 20. When the due day is a weekend or a holiday, it moves to the next working day, and the holiday list for that year is the one on the due dates page.
A seller who both reports and pays by the due day may take a timely discount equal to 0.5 percent of the tax. A seller who pays ahead may take that same 0.5 percent and also 1.25 percent tied to the prepayment. Show up late with the report and the penalty is 50 dollars. Pay the tax anywhere from the first day late through day 30 and the added share is 5 percent. Pay after those 30 days and the added share is 10 percent. Sales tax that is still unpaid also starts interest on day 61, with the percent left on the interest page.
Stay under 500,000 dollars of Texas revenue across the prior twelve calendar months, as a remote seller, and you are in the safe harbor the Comptroller describes. Sales a marketplace made still count in that 500,000 dollars even if the marketplace collected the tax. A seller who is located in Texas and who sells only by marketplace still has to hold a permit, since physical presence follows from being here. Keep the gross receipts records for four years at least. Form 01-339 is the certificate for resale and for exemption, and holding a permit number does not take the place of that certificate. Tax comes due if a buyer later uses something that was purchased for resale. Pull a broom out of inventory and use it to sweep the store, and the Comptroller treats that pull as a use the tax can reach.
The two of you should be able to open the sales tax month the same way you open the books. Sales from your own site, sales through a marketplace, exempt sales with a certificate already on file, and items pulled out for the shop's own use are four different lines. Mix those lines and the K-1 and the sales tax return start telling two stories about one year.
What we will do on the call
Bring the agreement, the last K-1, and any Texas report or information report the two of you already signed. Say at the start of the hour if nobody signed the May report. The hour still happens. The gap gets a name, and we keep going with the paper that did arrive.
We will say whether the company, in the form you actually created, still looks like a name Publication 98-806 lists. We will say whether last year's revenue sat under the line for that report year or over it. We will say whether a distributive share, a guaranteed payment, and a 1099 have been kept in separate piles. The call does not include a fee quote, and the company is not a client when the call ends.
A report that tells a lender the statements are fair is a different product, and that product sits outside this practice. The franchise report and the sales tax return are outside that product too. What we can talk about is computing the margin from a month that has closed, preparing the information report, and keeping the sales tax lines apart.
Both of you are welcome on the same screen. We will not choose a side about which of you should have signed the May report. If the honest reading is that the federal return is the only paper this year needs, you will hear that too.
Ask about the May report.
Say whether you formed a company, and whether a May report was signed.
You will be talking to the Steven Palmieri practice.